Loren Asmus, founder of UTXO Management, emphasized at the recent Bitcoin Treasuries conference that Bitcoin should be regarded as a permanent portfolio component. He contended that the asset’s risk-adjusted return profile justifies a dedicated allocation, echoing the shift seen after the introduction of Bitcoin ETFs. According to Asmus, many institutions now allocate roughly 2.5% of their capital to Bitcoin, moving from a position of skepticism to one of sustained participation.
Bitcoin versus the $300 Trillion Bond Market
Asmus positioned the massive global bond market as the logical next step for institutional Bitcoin exposure. He described Bitcoin as functioning similarly to a credit-default swap that protects against monetary debasement, offering a hedge that traditional fixed-income instruments cannot provide. By framing the cryptocurrency as a bridge to the bond universe, UTXO Management aims to capture the yield-seeking behavior of investors while preserving Bitcoin’s unique scarcity characteristics.
Portfolio Fit and Volatility Considerations
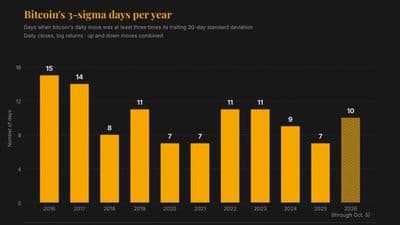
While acknowledging Bitcoin’s inherent volatility and periodic drawdowns, Asmus argued that its correlation profile and non-cash-flow nature can enhance diversification. He noted that the denominator for evaluating Bitcoin differs from income-producing assets, requiring a distinct underwriting approach. UTXO’s own hedge-fund structure incorporates a preferred-income strategy to generate stable returns alongside Bitcoin exposure.
The Real Barrier: Education
Despite growing interest, Asmus identified a lack of understanding as the chief impediment to broader institutional participation. He highlighted that once an organization commits capital, the likelihood of continued involvement rises sharply. The challenge lies in communicating Bitcoin’s role as a defensive asset rather than a speculative play, and in clarifying the sources of capital that can flow into such strategies.
Long-Term Allocation Outlook
From a strategic standpoint, Asmus presented a nuanced view of buying opportunities versus warnings. He suggested that a disciplined, long-term allocation—rather than short-term trading—aligns with the asset’s historical risk-adjusted performance. The focus, he argued, should be on integrating Bitcoin as a structural allocation that complements existing fixed-income holdings.
Why it matters
If institutions begin to treat Bitcoin as a core component comparable to bonds, the resulting capital inflows could reshape asset allocation models across the financial industry. Understanding Bitcoin’s potential as a hedge against monetary debasement and its role within a diversified portfolio may drive a new wave of institutional adoption, provided that the educational gap can be bridged.