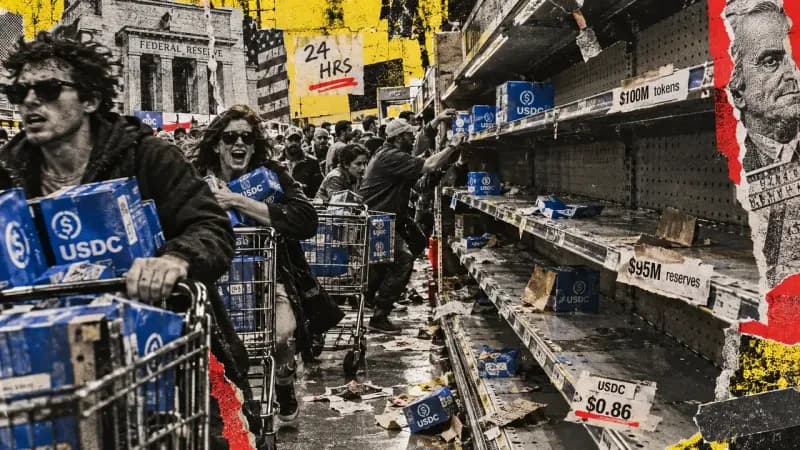
The Federal Reserve’s draft regulation for payment-stablecoin issuers sets a rapid response timer. If an issuer’s reserve assets dip below the value of its circulating tokens, it must alert the Fed within 24 hours and present a remediation plan. Should the shortfall persist, the issuer is required to start liquidating its reserves and redeeming tokens by 5 p.m. on the next business day – a window that can be under 48 hours in many scenarios. Daily reporting of fair-value reserves at 5 p.m. local time of the supervising Reserve Bank would become mandatory, and issuers operating close to the threshold may need to perform the calculation multiple times per day.
Impact of continuous minting
Unlike a hard stop on issuance, the proposal permits the creation of new tokens during the remediation period, tying this choice to the public nature of blockchain data. An abrupt pause would be immediately visible to observers, potentially alerting token holders to a liquidity problem and accelerating withdrawals. The Fed argues that allowing limited minting can spread the existing reserve gap across a larger supply, modestly improving per-token coverage. However, the model shows that each additional token dilutes the backing, meaning new buyers may absorb part of a pre-existing loss.
Comparison with OCC approach
The Office of the Comptroller of the Currency (OCC) has taken a contrasting stance. Under its draft rule, an issuer that falls below the minimum reserve ratio must cease net new issuance instantly, with a narrow exception for moving tokens between ledgers. Mandatory liquidation would only be triggered after the shortfall endures for 15 consecutive business days, a period the OCC could extend. Because the Fed’s rule applies to entities it supervises while the OCC and state regulators oversee others under the GENIUS Act, both regimes could operate side-by-side, creating divergent compliance pathways for stablecoin projects.
Potential market effects of a run
Recent market stress highlighted how quickly a stablecoin can lose parity. During a weekend when banking rails were offline, USDC briefly traded at $0.86, and secondary-market volume surged to nearly $2 billion within a single hour. The broader stablecoin market totals roughly $307 billion, with USDT accounting for about $184 billion and USDC around $76 billion. A rapid redemption wave could push holders into Bitcoin, other stablecoins, or fiat, thinning order-book depth and widening spreads across trading pairs. The Fed notes that visible redemptions on-chain can trigger further withdrawals, while secondary markets may absorb some selling pressure that would otherwise hit the issuer directly.
Why it matters
The Fed’s hourly crisis clock introduces a much tighter timeline for addressing reserve deficiencies than existing supervisory frameworks. By allowing limited minting during remediation, the rule seeks to avoid a sudden on-chain signal of distress, yet the very act of continued issuance could still be interpreted as a warning. The coexistence of Fed and OCC rules may lead to a fragmented regulatory landscape, where stablecoin issuers must navigate differing remediation triggers and liquidation thresholds. Market participants should monitor how these proposals shape liquidity dynamics, especially given the sizable role stablecoins play in crypto trading and the potential for rapid cross-asset flows during a crisis.


