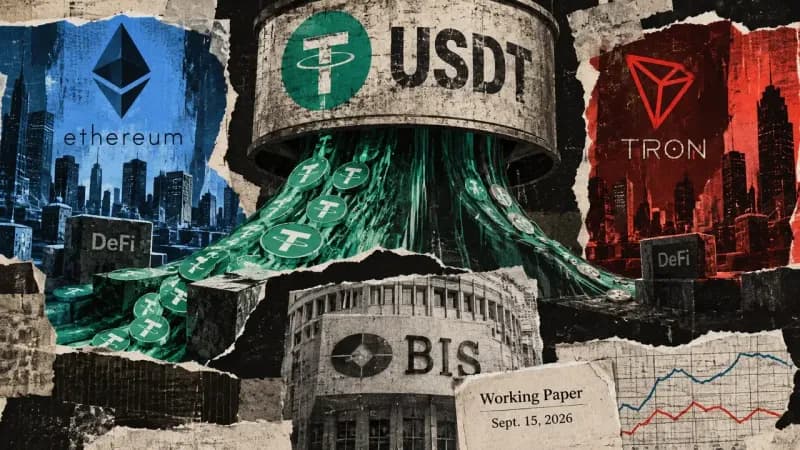
The Bank for International Settlements released a working paper that examined how Tether (USDT) is distributed across account types on Ethereum and Tron up to the end of 2024. Although the overall supply of USDT expanded markedly, the proportion residing in smart-contract addresses – the typical proxy for decentralized-finance activity – declined. On Ethereum, contract holdings fell from a peak of about 20% in 2021-22 to roughly 10-15% by late 2024. Tron’s contract share remained near 1% throughout the period.
How the analysis was conducted
Researchers reconstructed token balances by parsing transfer event logs on both chains. They identified contract addresses from deployment records and treated all other addresses as externally owned accounts. The token’s mint, burn and blacklist-destruction events were cross-checked to ensure the reconstructed supply matched on-chain totals. This approach follows each USDT token across all addresses, rather than aggregating deposits reported by individual DeFi protocols, which can double-count the same tokens.
Why the share decline matters
A falling percentage does not necessarily mean the absolute amount held in contracts fell; rather, the growth in total USDT outpaced the increase in contract balances. The paper notes that contract-held USDT on Ethereum hovered in the low-tens-of-billions of dollars, while the overall supply rose, diluting the share metric. Consequently, using the contract-share figure alone to infer a withdrawal of capital from DeFi would be misleading.
Limitations of the metric
Smart contracts can serve many purposes beyond lending or trading, such as bridges, wrappers or custodial services. Conversely, externally owned accounts may hold tokens for payments, savings, exchange custody or other uses. Therefore, the contract-share statistic cannot directly indicate the level of DeFi deployment or payment activity. Moreover, the BIS data stop before September 2026, so they do not reflect the most recent balances shown by services like DefiLlama, which reported about $73 billion of USDT on Ethereum and $92 billion on Tron as of late September.
Implications for market analysis
The findings challenge a common narrative that rising stablecoin supply automatically signals expanding DeFi demand. Analysts and investors should be cautious about equating total USDT volume with deeper protocol usage. More granular data that separates bridge, custodial and genuine DeFi contracts would be needed to assess true adoption.
Why it matters
Understanding where stablecoins actually reside is essential for gauging the health of the decentralized-finance ecosystem. If most new USDT is flowing into wallets rather than into DeFi contracts, the sector’s growth may be overstated. This nuance affects risk assessments, capital allocation decisions and regulatory perspectives on stablecoin usage across blockchain networks.