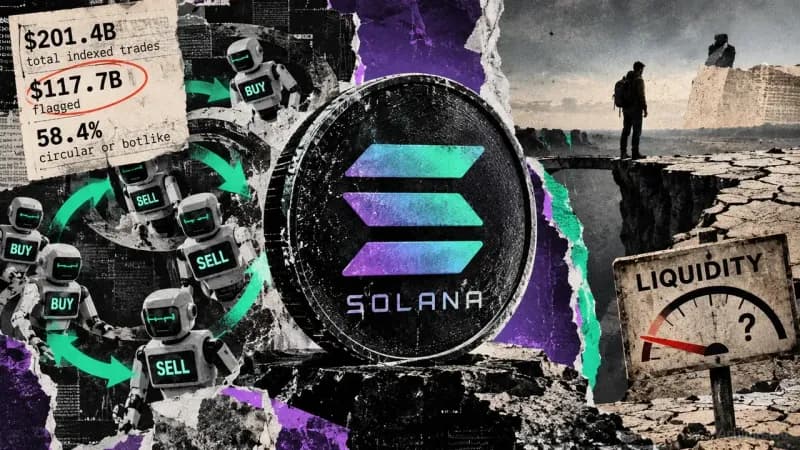
Recent analysis indicates that a substantial portion of recorded trading on Solana’s decentralized exchanges stems from repetitive, bot-driven activity rather than distinct user orders. The findings raise questions about the true depth of liquidity available to ordinary traders.
Methodology and Findings
A blockchain data firm examined $201.4 billion of Solana DEX trades priced in SOL, USDC or USDT over a 30-day window ending September 22. Using internal rules, it classified 58.4% of that sample as circular or bot-like behavior. Roughly $111.6 billion, or 95% of the flagged total, consisted of buying and selling the same token through the same pool inside a single transaction. One example from September 14 showed a wallet purchasing a token called Claude from a PumpSwap pool while another wallet sold nearly the same amount back in the same block, with both parties signing the trade and the pool recording about $2 000 of volume. The token name bears no relation to Anthropic.
The firm also identified two clusters of wallets—one group of 20 and another of 50—that displayed strikingly similar trading patterns. Together these clusters contributed $26.3 billion to the flagged amount. Wallets were grouped by volume and token variety, without tracing their funding sources. A small set of bots was said to gain a three-times advantage by routing trades through a proprietary protocol.
Comparison with Alternative Data
On September 24, a rival analytics dashboard reported a rolling 30-day Solana DEX volume of $75.9 billion. The data firm’s window ended two days earlier, making a direct subtraction of its flagged $117.7 billion from that figure misleading due to differing dates and pool coverage. When comparing the same period, the firm said $83.7 billion of its indexed trades fell outside its flagged category, while the rival dashboard counted $78.8 billion across the chain for August 24 through September 22. The firm noted the similarity was partly coincidental: the rival includes venues it misses and excludes pools it keeps. The $83.7 billion remainder remains an unresolved measure of activity that could stem from independent users.
On PumpSwap, the rival’s methodology counts pools that have a specified quote token, at least $5 000 in total value locked, and a minimum of 50 unique traders. Its adapter enforces those thresholds. In contrast, the data firm screens transactions and wallet behavior directly, arguing that pool balances and trader counts alone cannot confirm whether addresses represent separate individuals.
Liquidity Depth Concerns
The specific Claude/SOL pool used in the September 14 example showed effectively empty reserves and $0 liquidity in a GeckoTerminal snapshot taken September 24. Its historical trading record could still be large, yet a new trader encountering the pool at that moment would face negligible liquidity. Evaluating real execution depth requires a token pair, trade size, and timestamp, as described in Jupiter’s swap documentation where a quoted expected output may differ from the actual result due to price movement before the quote is used.
To estimate liquidity after removing round-trip trades, analysts would need historical reserves, comparable routes, and realized fill data for both flagged and unflagged pools. The volume total alone supplies none of those measurements. Moreover, the investigated pools sit alongside distinct Solana markets; an April report by Jump Crypto examined March fills in SOL/stablecoin pairs run through proprietary automated market makers. Jump participates in that market, and its results do not describe execution in the PumpSwap pools flagged by the data firm, so one segment’s findings cannot be extrapolated to the chain’s overall liquidity standing.
Fee metrics also offer an incomplete picture. The rival’s chain-fee table tracks a separate measure from PumpSwap’s liquidity-provider, protocol, and creator fees. Neither turnover nor fee totals reveal the price impact a particular order would experience.
Why it matters
The $117.7 billion figure applies only to indexed pools and the firm’s rule set, while the spendable depth left for ordinary users remains unmeasured. Solana’s competitive position in execution quality will depend on pair- and size-specific fills across comparable venues, not on aggregate turnover that may be inflated by repetitive, bot-driven activity.


